Understanding Canada’s Voluntary Disclosures Program (VDP)

The Canada Revenue Agency (CRA) Voluntary Disclosures Program (VDP) gives individuals and businesses a single opportunity to fix past tax issues before the CRA finds them. If accepted, the program can offer relief from penalties, interest, and prosecution. But it's not automatic, and not every application gets accepted.

If you're also working with provincial sales taxes (e.g., PST in BC, MB, SK), each province administers its own VDP with separate processes and relief structures—and they are not bound by CRA’s rules.

At Forbes Andersen LLP, we’ve guided clients across Canada and internationally through successful disclosures involving unfiled tax returns, missed foreign reporting, GST/HST compliance gaps, and even provincial PST issues. Our hands-on approach ensures you meet the strict eligibility requirements with a complete and credible submission.

What is the Voluntary Disclosures Program?

The VDP allows taxpayers to proactively correct errors in previously-filed returns or submit filings that were missed altogether. Originally launched to encourage tax compliance, the program has rigorous and structured processes for taxpayers to restore tax compliance.

Types of taxes and compliance issues under federal and provincial tax statutes include:

  • Personal, corporate, trust, and partnership income tax returns
- Missed filings, unreported income, incorrect expense claims, or late-filed returns.
  • Foreign income and asset reporting obligations
- Late or inaccurate filings for:
  • T1135 (Foreign Income Verification Statement)
  • T1134 (Foreign Affiliate Reporting)
  • Other forms related to offshore holdings, foreign trusts, and specified foreign property.
  • GST/HST returns and remittances
- Includes unfiled returns, under-reported revenue, missed self-assessments, and unremitted collected tax.
  • Ineligible or incorrectly claimed Input Tax Credits (ITCs), Unremitted ITCs, late filings, or incomplete filings.
  • Payroll compliance issues - Unremitted source deductions, late T4 filings, or incorrect employee vs. contractor treatment.
  • Non-resident compliance failures
- Unreported rental income, withholding tax errors, or missed NR4/T1261 filings.
  • Provincial tax issues where applicable (e.g., BC PST, ON EHT)
- We coordinate with provincial authorities when disclosures affect both federal and provincial regimes.

It is important to understand that this is not a tax forgiveness program! It is a structured form of penalty and interest amnesty Canada provides in exchange for voluntary compliance. Acceptance depends on meeting the CRA’s and/or provincial taxation authority’s criteria in full.

Eligibility Criteria for the VDP (Federal)

To qualify under the CRA Voluntary Disclosures Program, your submission must satisfy all five of the following conditions:
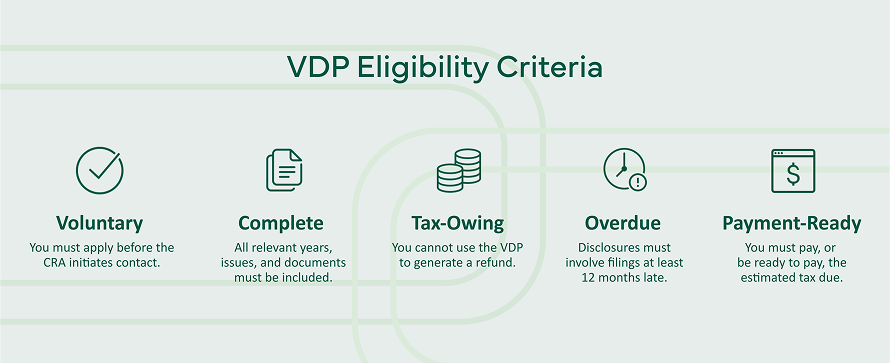
Once CRA acknowledges your application with an Effective Date of Disclosure (EDD), you have 90 calendar days to submit a complete package. We assist from the outset by preparing, calculating, and submitting the completed application required for CRA acceptance.

Benefits of Participating in the VDP

If accepted, the VDP can provide meaningful relief:

  • Elimination or reduction of penalties
  • Protection from criminal prosecution
  • Possible partial interest relief
  • Confidence that your tax affairs are now fully compliant

The VDP Application Process

Here’s how the VDP application process unfolds:

  1. Initial Assessment – We review your situation in detail, including all past filings, potential liabilities, and eligibility.
  2. Documentation Gathering – You'll need to collect relevant records and tax slips. We assist with reconstructing data when necessary.
  3. Form RC199 Completion – This is the core VDP form submitted to the CRA. We complete it on your behalf, ensuring full alignment with CRA expectations.
  4. Formal Submission and Follow-Up – Forbes Andersen manages all CRA correspondence, follows up on processing, and addresses any red flags proactively.

General Program vs. Limited Program

The CRA assesses each application under one of two streams:

General Program

  • Relief from most penalties, including gross negligence  
  • Partial interest relief for earlier tax years  
  • The right to object or appeal any reassessments remains intact

Limited Program

  • No relief from gross negligence penalties  
  • No interest relief
  • You must waive your right to object or appeal reassessments

We work strategically with our clients to position their case under the General Program whenever possible. This can make a significant difference in the financial outcome and future flexibility regarding CRA decisions.

GST/HST Wash Transaction Program

The Wash Program is a specialized component of the CRA’s GST/HST VDP. It is used when:

  • A supplier collected GST/HST but failed to remit it
  • The purchaser was entitled to a full input tax credit (ITC)
  • There was no net tax loss to the government

The CRA recognizes that no harm was done to the public purse in such cases and may offer more leniency. We help evaluate eligibility and build these submissions accordingly.
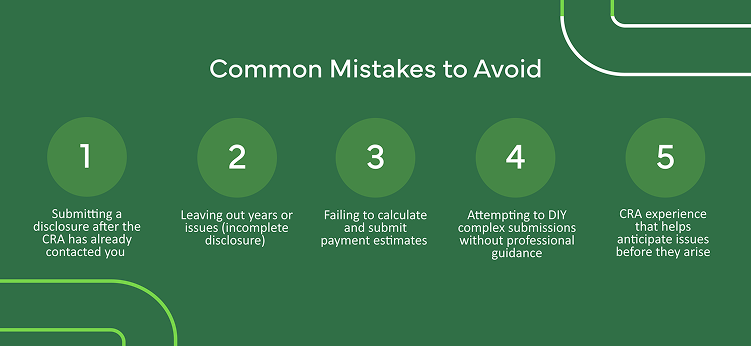
In one instance, a taxpayer (before becoming a client) misjudged the scope of disclosure needed and triggered a CRA audit. When we were brought in later, we could only do limited damage control. Don’t risk that outcome.
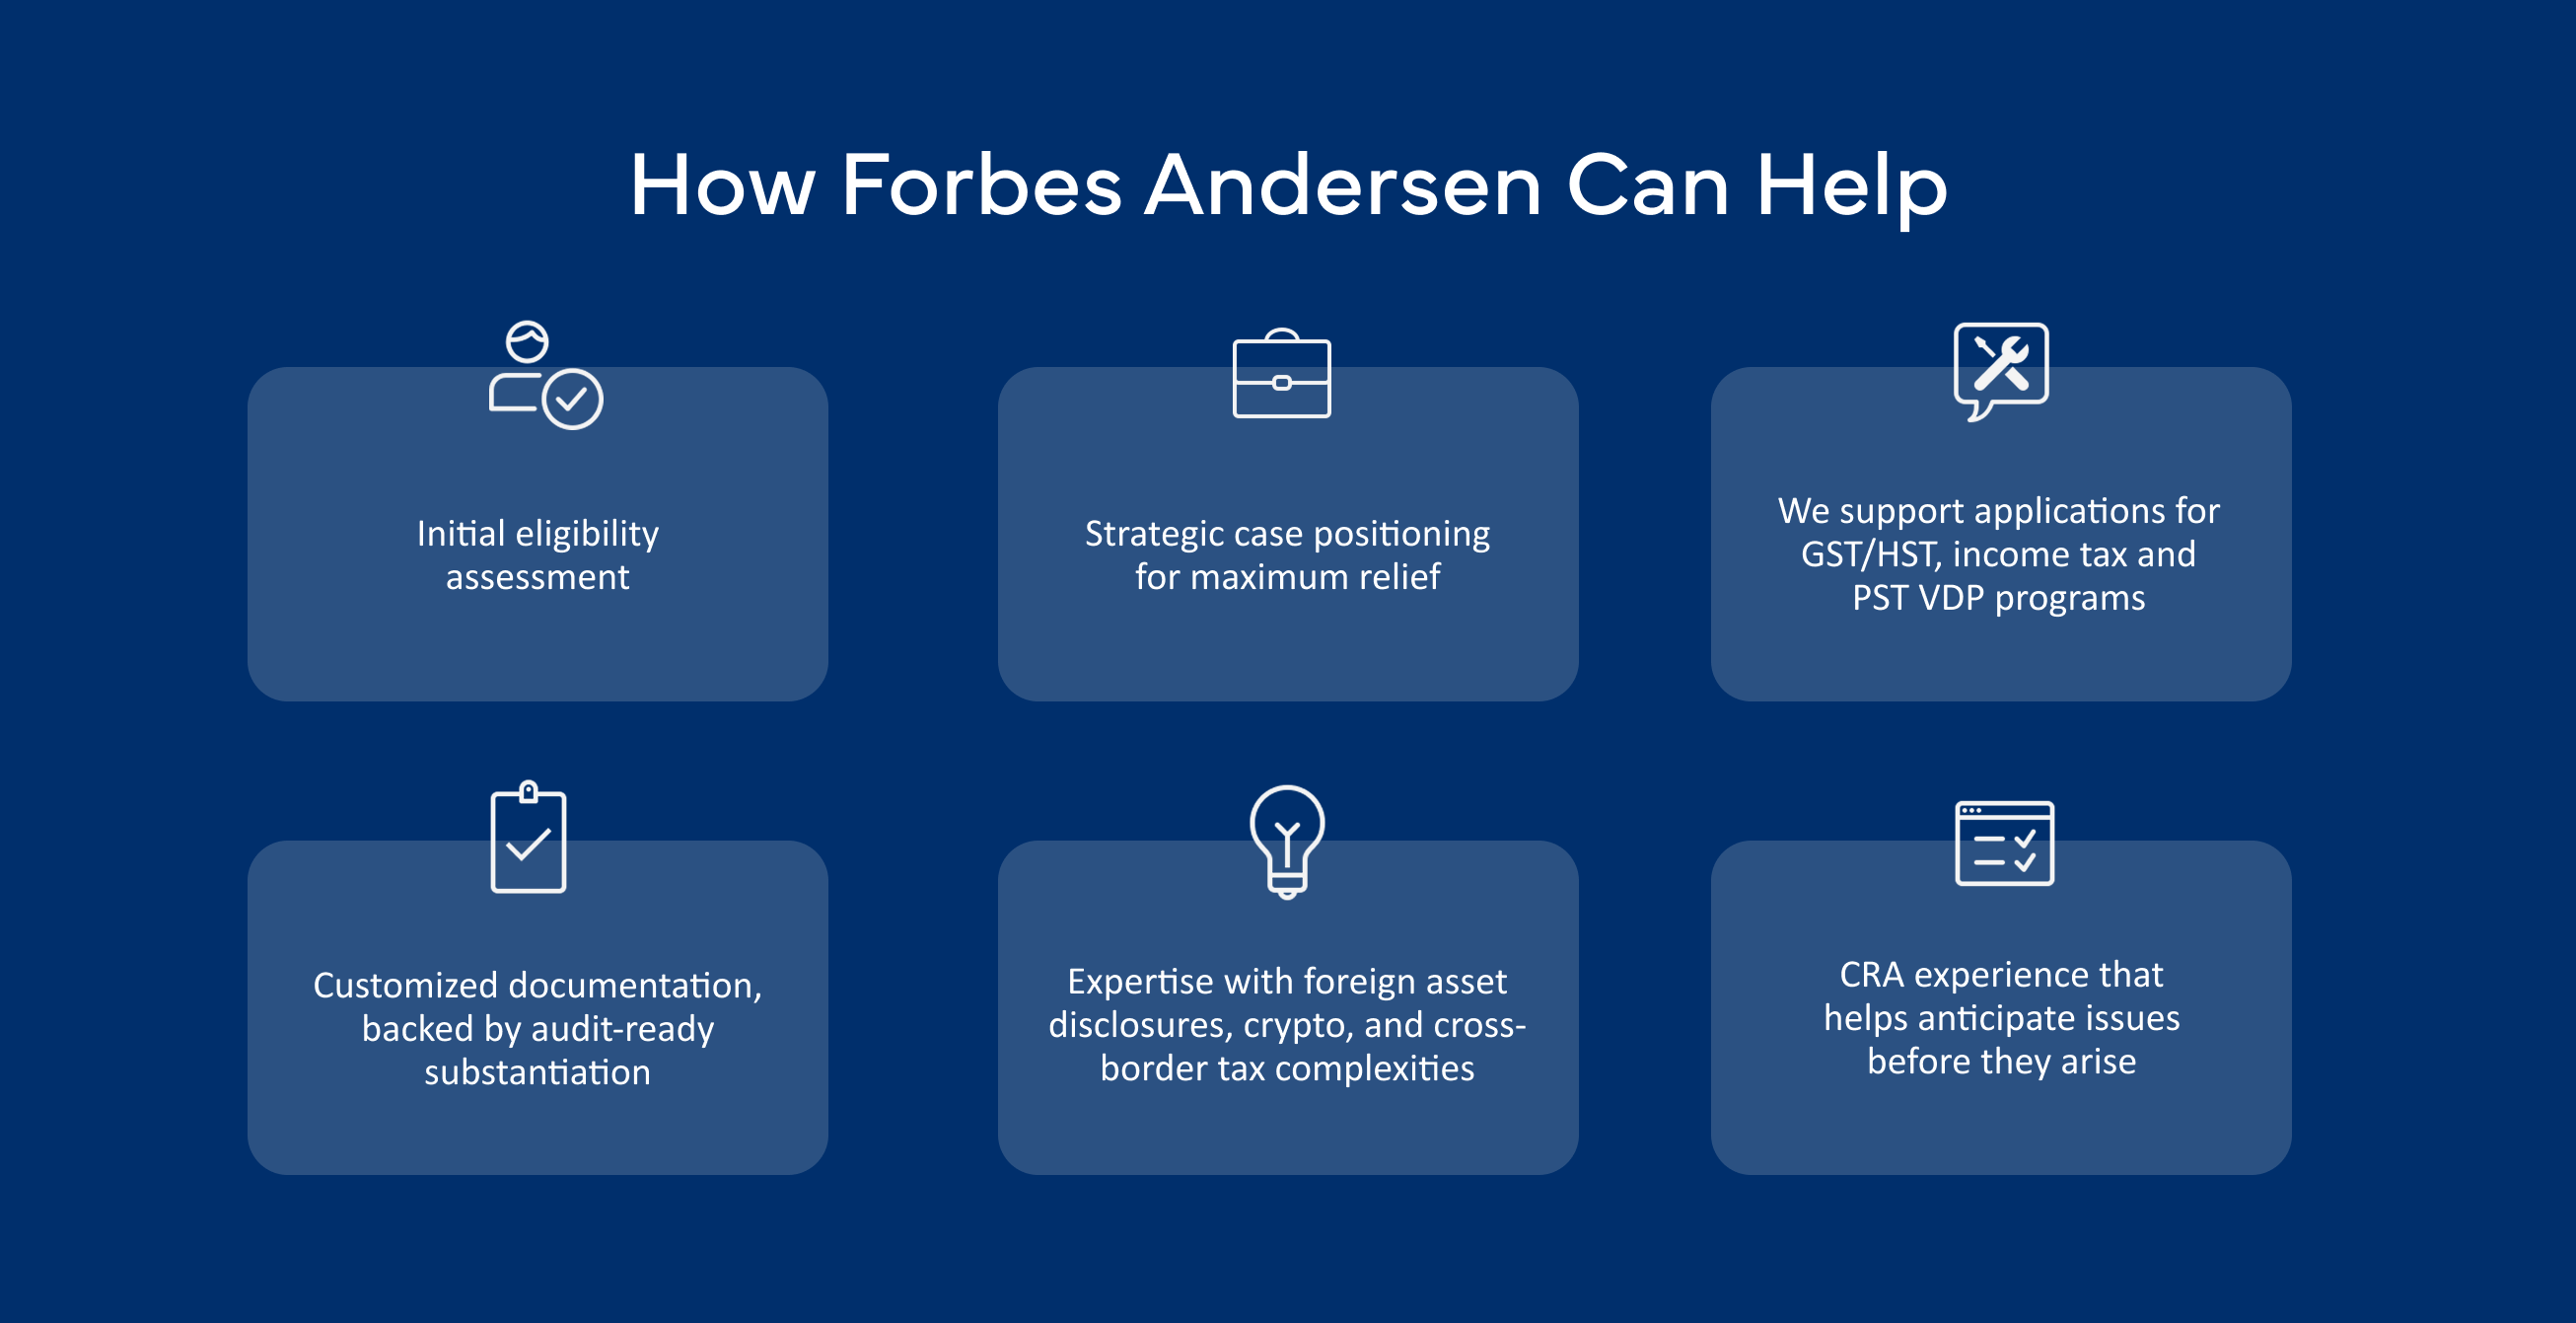
We take the guesswork out of disclosure so you can move forward with clarity and confidence. We’ve handled disclosures for individuals, professionals, self-employed Canadians, non-residents, estates, and corporate entities. No two files are the same, and we never treat them that way!

Recent Forbes Andersen Client Outcomes

✔ Toronto entrepreneur: Six years of missed foreign disclosures (T1135). Penalties and interest fully waived.

✔ Foreign corporation: PST and HST filing issues across provinces resolved. No audit triggered, no penalties.

✔ Retired couple: Late foreign income reporting completed. Avoided both penalties and interest.

Conclusion: Don’t Wait for the CRA to Call

If you're considering the VDP, timing is everything. Once the CRA contacts you - even by phone or letter - the VDP window closes. Take control of your compliance today.  We’ll help you resolve past tax issues efficiently, discreetly, and strategically.

Julian Lombardo, CPA, CA is a partner at Forbes Andersen LLP. If you would like additional information or clarification regarding Voluntary Disclosure Programs or other tax issues, Julian can be reached at julian.lombardo@fa.ca or 416-947-0464 ext 230.
All Blog Posts

Related Articles

Q4 2026 tax tips and traps from Forbes Andersen LLP
October 20, 2026

Q4 2026 Tax Tips & Traps: Tax Updates for Canadian Businesses

A proposed immediate write-off for business assets, worker status and FHSA updates, and CRA reassessment risks. Read the full Q4 2026 roundup.
Read more
Estate planning in Canada - business succession planning by Forbes Andersen LLP in Toronto
October 15, 2026

Estate Planning in Canada Part Three: Business Succession Planning

Succession planning is a subset of estate planning, but for business owners it is usually the biggest piece. Transition routes, what the tax planning is doing, who does which part of the work, and when to start.
Read more
Going Public in Canada Part Three: Life as a Public Company. A Forbes Andersen LLP article.
September 29, 2026

Going Public in Canada Part Three: Life as a Public Company

Continuous disclosure, quarterly reporting, audit committees, and the real cost of staying public. Forbes Andersen explains life after going public in Canada.
Read more
Estate Planning in Canada Part Two: Pre-Death Planning, Forbes Andersen LLP guide for business owners and families
September 2, 2026

Estate Planning in Canada Part Two: A Guide for Business Owners

The tax bill your estate owes is not fixed. Here's how business owners and families can reduce estate taxes through planning while there is still time.
Read more